Xtranet Technologies share analysis: is the 143% post-IPO rally already priced in?
Xtranet Technologies Ltd (NSE: XTRANET, BSE: 544838) closed at ₹308.25 on 16 October 2026, up 143% from its ₹127 IPO price in under three months. This Xtranet Technologies share analysis asks whether the business has earned that re-rating. We rebuild the numbers from the RHP, the Q1 FY27 filing and the earnings call, then test management's ₹500 crore FY27 revenue target against the order book, the cash flow and the valuation.
- Re-rating: the stock trades at about 37x trailing earnings (TTM PAT ₹43.4 crore) versus 16.3x at the IPO price.
- Margins are real: Q1 FY27 (Apr–Jun 2026) EBITDA margin rose to 20.6% from 12.0%, as services climbed to 65–68% of revenue.
- Guidance is a stretch: hitting ₹500 crore needs Q2–Q4 FY27 revenue 41% above the same period of FY26; roughly half must come from orders not yet won.
- Cash is the weak spot: free cash flow was negative in each of FY23–FY26, a cumulative –₹48 crore.
- Our model: a probability-weighted value of about ₹337 (bear ₹147 / base ₹350 / bull ₹588), only ~9% above the current price.
Why did the Xtranet share price rise 143% after the IPO?
The stock re-rated because Q1 FY27 showed margins near 21% and management guided to 35–40% growth, against an IPO priced at only 16.3x FY26 earnings. The ₹166.8 crore issue was subscribed 12.24 times, listed at ₹136 on 30 July 2026, and then more than doubled.
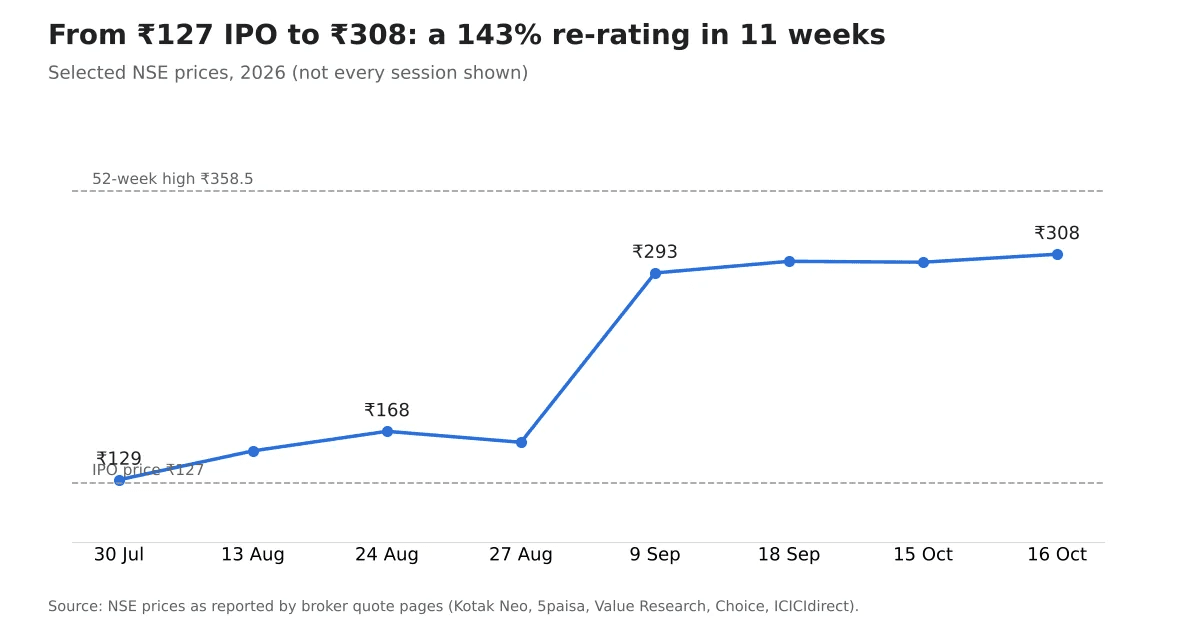
Most of the move came in early September, after the Q1 results (19 Aug) and the earnings call (24 Aug). The stock touched a 52-week high of ₹358.50 and now sits about 14% below it. The market cap has gone from ₹664 crore at the issue price to about ₹1,612 crore.
What does Xtranet Technologies do?
Xtranet is a Bhopal-based IT services firm, founded in 2002, that builds and runs data centres, ERP systems and digital platforms, mostly for government and PSU clients. It earns money from fixed-price projects, time-and-materials work and multi-year managed-service contracts.
| Vertical | Share of Q1 FY27 revenue | What it covers |
|---|---|---|
| Data centre infrastructure & IT operations | 48% | Data centres, disaster recovery, networks, cybersecurity, managed operations |
| Enterprise applications | 26% | ERP implementation, system integration, cloud |
| Proprietary platforms | 14% | XtraTrust (digital signatures, PKI), Synergy low-code platform |
| Digital services | 12% | IaaS, PaaS, SaaS, digital transformation |
The hidden gem is XtraTrust, one of about 11 private Certifying Authorities licensed in India to issue Digital Signature Certificates. Management says it has roughly 8.5 lakh subscribers on recurring plans, and its turnover rose from ₹11.1 crore in FY24 to ₹25.4 crore in FY26. Xtranet put another ₹15.25 crore into it in August 2026 to meet the licensing net-worth rule.
How did Xtranet perform in Q1 FY27?
Q1 FY27 (Apr–Jun 2026) was a margin quarter, not a growth quarter. Revenue rose 10.5% to ₹50.5 crore, but net profit jumped 77.9% to ₹6.04 crore as EBITDA margin widened by 855 basis points.
| Metric (consolidated) | Q1 FY26 | Q1 FY27 | YoY change |
|---|---|---|---|
| Revenue from operations (₹ crore) | 45.66 | 50.46 | +10.5% |
| EBITDA (₹ crore) | 5.50 | 10.38 | +89% |
| EBITDA margin | 12.0% | 20.6% | +855 bps |
| Net profit (₹ crore) | 3.39 | 6.04 | +77.9% |
| EPS (₹) | 0.89 | 1.55 | +74% |
The driver is mix. Services rose to 65–68% of revenue from about 45% a year earlier, and the CFO said hardware deployment work earns only 6–8% EBITDA margin. Each point of mix shift toward services therefore lifts margins quickly.
The weak spot is the top line. A 10.5% growth rate is far from the 35–40% management targets, which puts the burden on the next three quarters.
Xtranet financials: three years of margin expansion
Between FY23 and FY26, revenue grew 64% to ₹365.3 crore while net profit rose about 7x to ₹40.7 crore. Return on equity stayed above 28% in each of FY24–FY26 (29.6% in FY26), the highest among the listed peers named in the RHP.
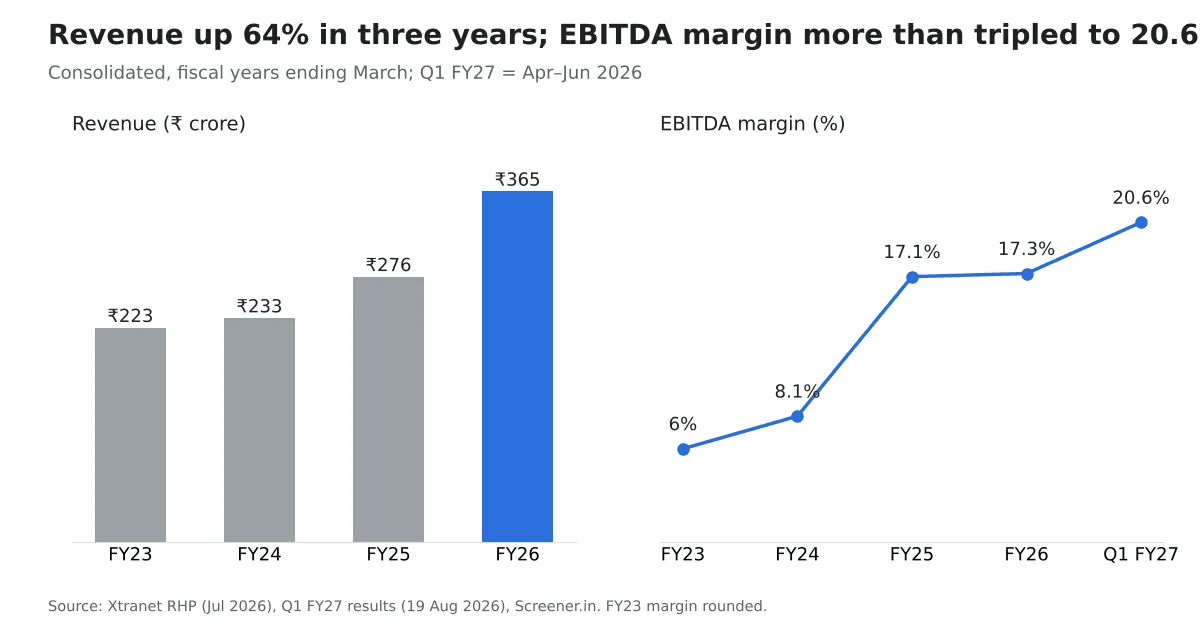
The step-change came in FY25, when EBITDA margin jumped from 8.1% to 17.1%. Managed services, digital services and platforms rose from 51.8% of revenue in FY24 to 64.8% in FY25, per the RHP. That is a structural mix shift, not a one-off.
Is Xtranet's profit backed by cash flow?
Not yet. Free cash flow was negative in every year from FY23 to FY26, adding up to –₹48 crore, while the company booked about ₹88 crore of net profit over the same years.
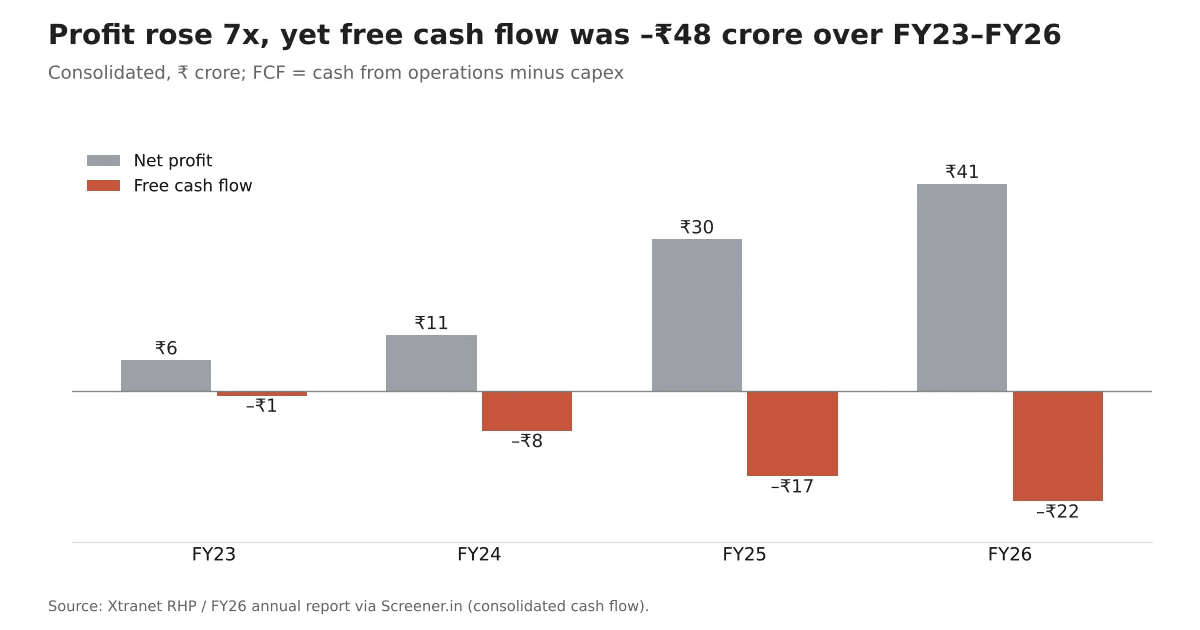
Two things drive the gap. Capex rose sharply (fixed assets plus work-in-progress went from ₹18 crore in FY24 to ₹85 crore in FY26) as the company built data-centre capacity. And government receivables are slow: the CFO puts deployment collection cycles at 120–150 days. Debtor days did improve, from 215 in FY25 to 114 in FY26, and operating cash flow reached ₹28 crore in FY26. The trend is right; the absolute cash is still thin.
Why is Q4 so important for Xtranet?
Because government projects bill at year-end. In FY26, the March quarter alone produced ₹161 crore, or 44% of annual revenue, and ₹24.2 crore of net profit. Q1 is seasonally the smallest quarter, at about 12.5% of the year.
| FY26 period | Revenue (₹ crore) | Share of FY26 |
|---|---|---|
| Q1 (Apr–Jun 2025) | 45.7 | 12.5% |
| Q2 + Q3 (Jul–Dec 2025) | 158.7 | 43.4% |
| Q4 (Jan–Mar 2026) | 161.0 | 44.1% |
| Full year | 365.3 | 100% |
Q2 + Q3 derived as full year minus Q1 and Q4 (the company was unlisted then).
This matters for anyone reading quarterly prints. A weak Q2 or Q3 is normal; a weak Q4 FY27 (Jan–Mar 2027) would be the real warning sign. Valuing the stock off Q1 profit, annualised, would badly understate earnings.
Can Xtranet hit ₹500 crore revenue in FY27?
It is possible but not covered by the order book. Management targets ₹500 crore-plus in FY27, 37% above FY26. Q1 delivered ₹50.5 crore, and about ₹205 crore of the ₹373 crore order book (30 Jun 2026) is executable this year. That leaves roughly ₹244 crore to be won and billed within nine months.
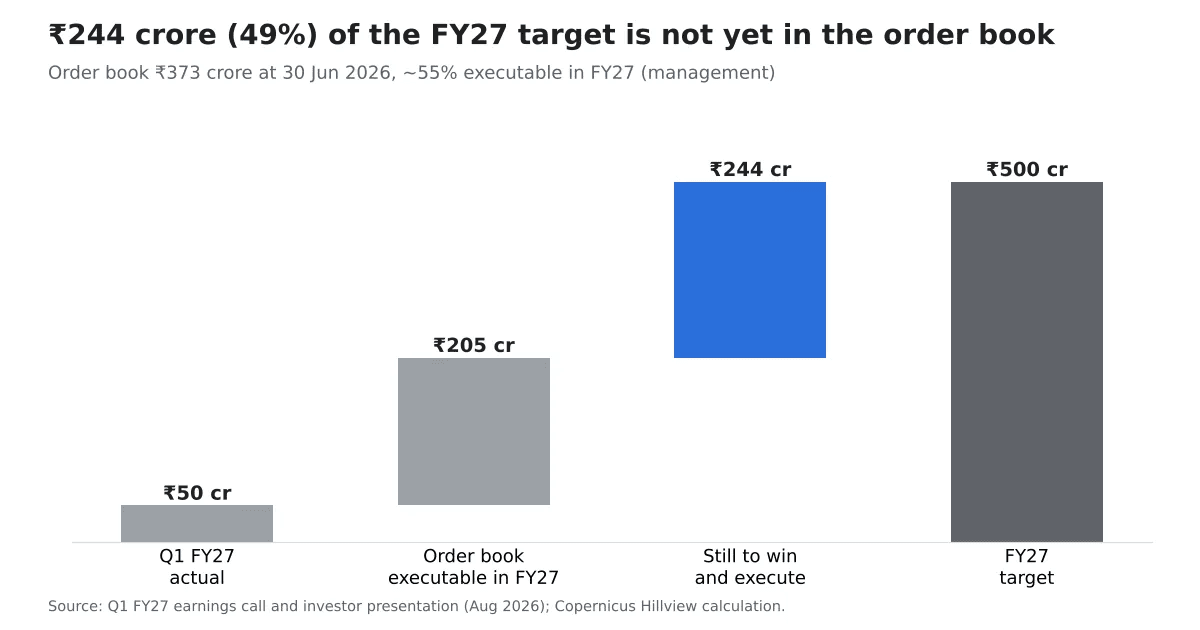
Put another way, Q2–Q4 FY27 revenue must reach about ₹450 crore, 41% higher than the ₹320 crore in the same months of FY26. Management points to a bid pipeline of about ₹1,200 crore, ₹60 crore of fresh orders in Q1, and a 43% win rate on direct government tenders in FY26 (91 of 214 bids). Bid-to-order cycles of 60–90 days for government work leave time to convert some of that pipeline. Our base case still assumes ₹470 crore (+29%), because large deployments take 12–15 months to go live.
Xtranet Technologies share analysis: is the valuation stretched?
On trailing numbers, yes. At ₹308.25 the stock trades at 37x TTM EPS of ₹8.30 and 5.4x estimated post-IPO book value of about ₹57 per share. On our base-case FY27 EPS of ₹10.8, the forward P/E is about 28x.
| Company | P/E on FY26 EPS | Note |
|---|---|---|
| Xtranet Technologies | 16.3x at IPO; ~37x TTM now | 16 Oct 2026 price |
| Allied Digital Services | 18.8x | Pre-listing peer data, Jul 2026 |
| CSM Technologies | 33.2x | Pre-listing peer data, Jul 2026 |
| Silver Touch Technologies | 70.2x | Pre-listing peer data, Jul 2026 |
| Trigyn Technologies | 81.0x | Pre-listing peer data, Jul 2026 |
Peer multiples will have moved since.
The peer range is wide (19–81x) and includes thinly traded names, so it says little on its own. The fairer test is earnings growth. Xtranet now trades on the kind of multiple that needs the 35–40% guidance to be delivered, not just approached.
What is the fair value of Xtranet share? Our scenario model
We value the stock 12 months out on FY28 (Apr 2027–Mar 2028) earnings, weighting three cases. These are our assumptions, not company guidance.
| Case (probability) | FY28 revenue | EBITDA margin | FY28E EPS | P/E | Value per share |
|---|---|---|---|---|---|
| Bear (30%) | ₹470 crore | 15.0% | ₹8.2 | 18x | ₹147 |
| Base (50%) | ₹600 crore | 18.5% | ₹14.6 | 24x | ₹350 |
| Bull (20%) | ₹720 crore | 20.0% | ₹19.6 | 30x | ₹588 |
| Probability-weighted | ~₹337 |
Assumptions: 5.23 crore shares, 23% tax, depreciation ₹10 crore, interest ₹4–7 crore.
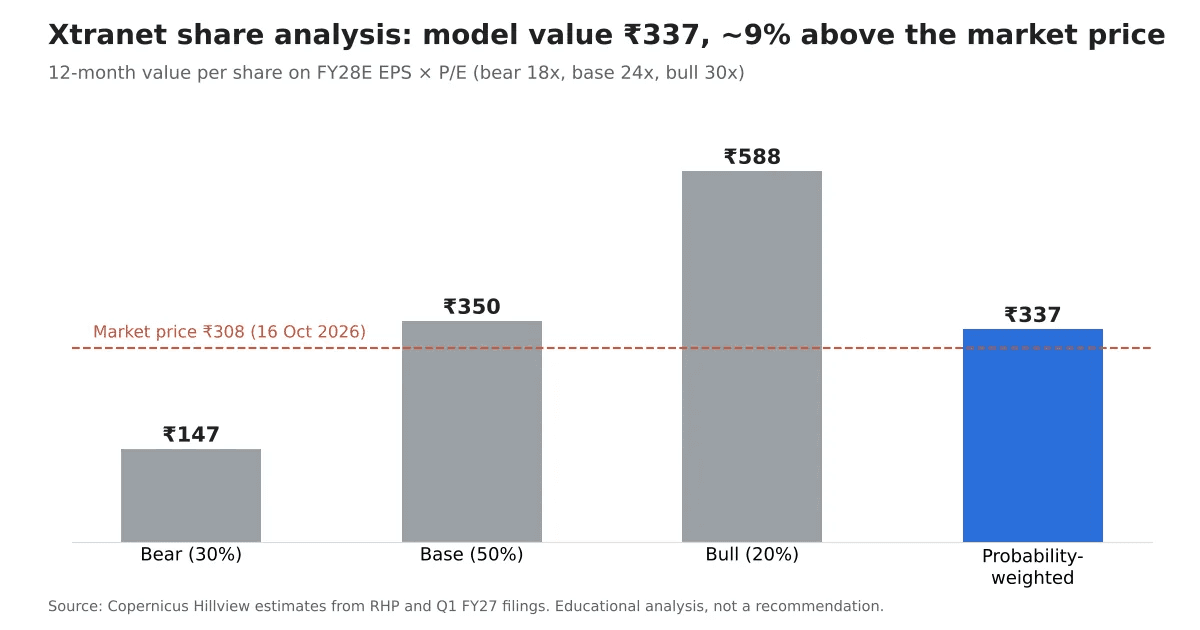
The weighted value comes to about ₹337, roughly 9% above the market price. The bull case is large, but the bear case (a services slowdown plus margin give-back) halves the stock. That skew is not attractive for fresh money at ₹308. In our model, the expected return reaches about 25% only below roughly ₹270.
For a data-centre play where the valuation still left room, see our Anant Raj data centre analysis.
What are the key risks for Xtranet investors?
The biggest risks are concentration, cash conversion and a valuation that leaves little room for a miss. These come from the company's own prospectus and call, not from market chatter.
- Client concentration: the top 10 customers made up 86.7% of FY26 revenue; government and PSU clients 47.1%.
- Geographic concentration: 85.7% of FY26 revenue came from Maharashtra, Madhya Pradesh and Delhi.
- Cash conversion: four straight years of negative free cash flow; government deployment receivables take 120–150 days.
- Contingent liabilities: ₹47.5 crore at 31 Mar 2026, about 31% of net worth, per the RHP.
- Hardware inflation: the CFO said hardware costs have risen 3–4x in a year, a threat to margins on fixed-price deployments.
- Supply overhang: the second half of anchor shares (about 19.7 lakh shares, ~3.8% of equity, ~₹61 crore at today's price) unlocks on 26 Oct 2026.
What should investors watch next?
Three dated events will test the thesis over the next six months.
- Q2 FY27 results (Jul–Sep 2026), due by mid-November 2026: watch services mix and whether margins hold near 20%.
- Fresh order announcements: about ₹244 crore of FY27 revenue still needs orders; wins above ₹50 crore each would be meaningful.
- Q4 FY27 (Jan–Mar 2027): the quarter that decides whether ₹500 crore is met. Also track the new XtraNet Data Centre Pvt Ltd subsidiary, formed on 9 Oct 2026.
Frequently asked questions
Is Xtranet Technologies a good stock to buy at ₹308?
Our model suggests the risk-reward is balanced rather than attractive at ₹308. The probability-weighted value is about ₹337, only 9% higher, while the bear case is ₹147. The business quality is improving, but the price already assumes most of the 35–40% growth guidance. This is educational analysis, not a recommendation.
What is the target price of Xtranet share?
We do not issue a target price. Our scenario model gives a 12-month value range of ₹147 (bear) to ₹588 (bull), with a weighted value of about ₹337 on FY28 estimated earnings. The base case of ₹350 assumes ₹600 crore revenue and an 18.5% EBITDA margin in FY28.
Why did Xtranet share price go up after listing?
The stock rose from its ₹127 IPO price to above ₹300 because Q1 FY27 profit jumped 78% and EBITDA margin hit 20.6%. Management also guided to ₹500 crore FY27 revenue. The IPO had been priced at a modest 16.3x earnings, leaving room for a re-rating.
What does Xtranet Technologies do?
Xtranet Technologies is a Bhopal-based IT services company founded in 2002. It builds and operates data centres, implements ERP systems, offers digital services, and owns XtraTrust, a licensed digital-signature certifying authority. Most work comes from government, PSU and large enterprise clients in India.
Is Xtranet Technologies debt-free?
No. Consolidated borrowings were ₹85.5 crore at 31 March 2026. About ₹20–22 crore of the IPO proceeds were earmarked to repay debt, and ₹102 crore to fund working capital. Debt is moderate against post-IPO net worth of roughly ₹297 crore, but cash flow remains negative.
When does the Xtranet anchor lock-in end?
The 30-day lock-in on half the anchor shares ended in late August 2026. The remaining 50%, about 19.7 lakh shares, becomes free to trade on 26 October 2026. That is roughly 3.8% of the company's equity.
Conclusion
This Xtranet Technologies share analysis finds a business that is genuinely improving: margins have more than tripled, XtraTrust adds a licensed recurring stream, and the order pipeline is large. But at 37x trailing earnings, with negative free cash flow and half the FY27 target still to be won, the stock prices in most of the good news. We would revisit the risk-reward after Q4 FY27 or nearer ₹270.
Related research: Jindal Supreme share analysis · Tonbo Imaging IPO analysis · Jio Platforms IPO 2026
Sources
- Xtranet Technologies — NSE quote page (NSE: XTRANET)
- Xtranet Technologies — BSE filings, scrip 544838
- Xtranet Technologies prospectus — SEBI filings, July 2026
- Xtranet Technologies FY26 Annual Report (BSE)
- Q1 FY27 earnings call transcript, 24 Aug 2026 (BSE)
- Xtranet Technologies company website
- Screener.in consolidated financials (secondary check)
This report is for information only and is not an offer or solicitation to buy or sell any security; views and estimates are as of the date of publication and may change without notice. Investments in securities market are subject to market risks; read all the related documents carefully before investing.